
Every growing business hits the same wall at some point. You have paying customers, steady demand, and a clear plan to scale — but not enough cash to move fast. This is where growth funding comes in.
The tricky part is not finding money. Money is out there. The tricky part is picking the right kind of money for your stage, your risk tolerance, and your long-term goals. Pick wrong, and you either give away too much of your company or take on debt you can’t service.
This guide breaks down the real funding options available in 2026, how to tell them apart, and how to prepare before you approach anyone with your hand out.
What Growth Funding Actually Means
Growth funding is capital used by a business that already has traction customers, revenue, or proven demand to scale further. It’s different from early-stage startup funding, which usually covers building a product or testing an idea for the first time.
If your business already earns money and you need capital to hire, expand into new markets, buy equipment, or increase production, you’re looking for growth funding, not seed money.
Investors and lenders treat these two situations very differently. Growth-stage businesses get evaluated on numbers: revenue trends, customer retention, margins, and cash flow. Early-stage businesses get evaluated mostly on the idea and the team.
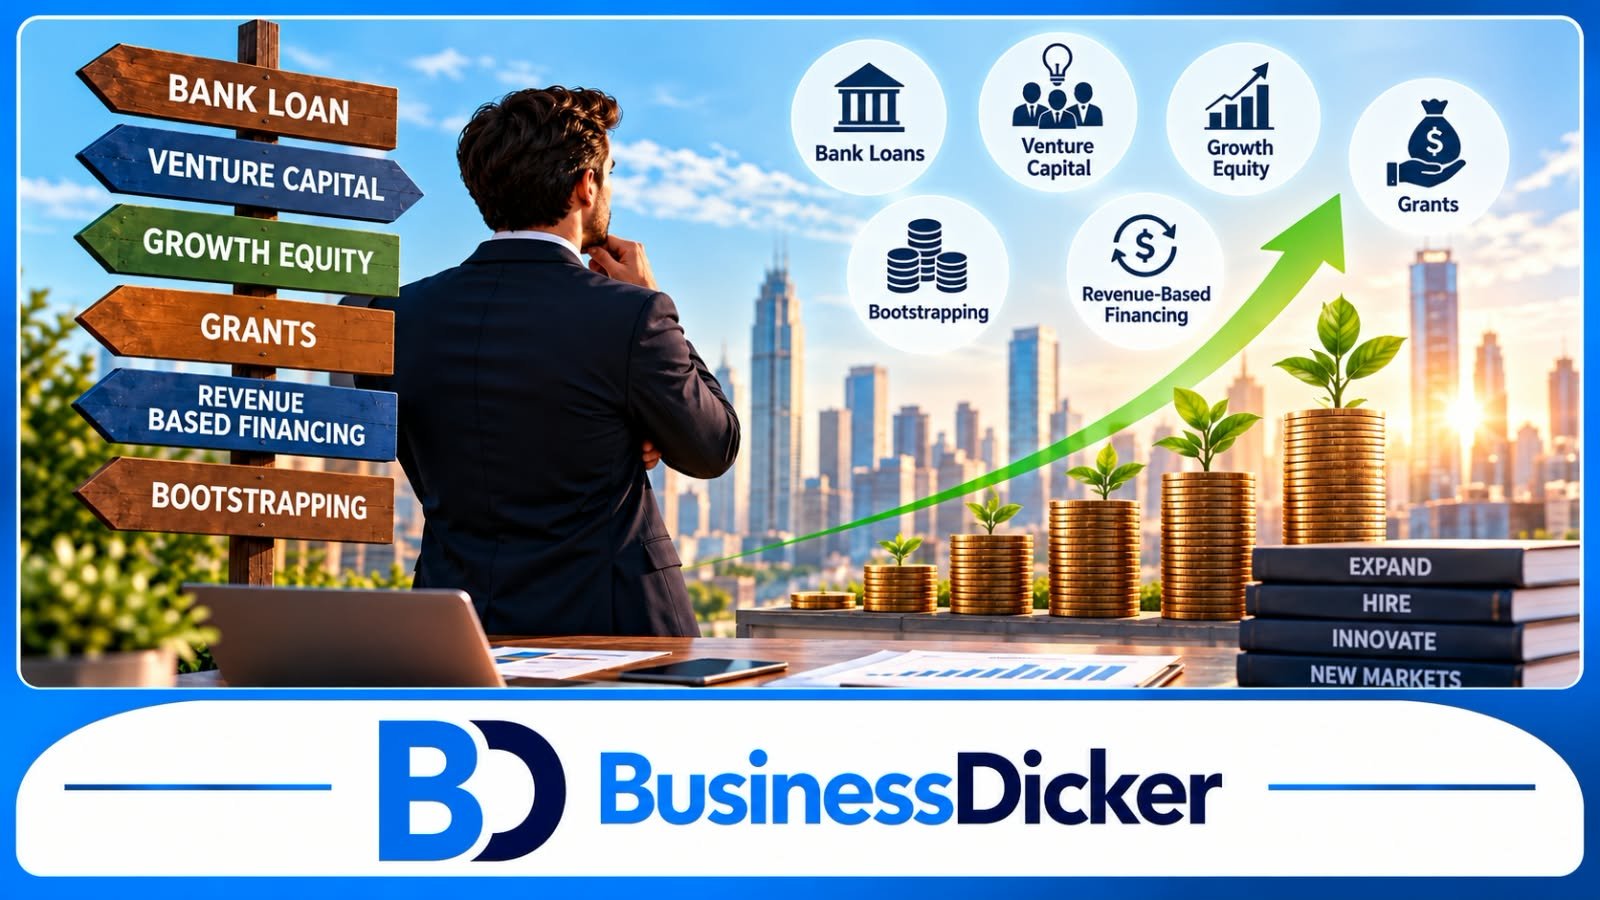
The Main Types of Growth Funding
There’s no single “growth funding” product. It’s a mix of options, and most businesses combine more than one.
Bootstrapping
This means using your own profits or savings to fund expansion. It’s slow, but you keep full control and owe nothing to anyone. Many founders recommend trying this first, even if you plan to raise money later, because it forces financial discipline early on.
Bank Loans and Business Lines of Credit
Traditional debt. You borrow a fixed amount and repay it with interest over time. Good if your revenue is predictable and you don’t want to give up equity. Banks will want to see two to three years of financial history before they approve anything meaningful.
Venture Capital
VC firms invest money in exchange for equity, betting on fast, large-scale growth. This suits businesses aiming to scale quickly across a big market. The trade-off is dilution — you give up a piece of ownership and, usually, some control over decisions.
Growth Capital / Growth Equity
This sits between venture capital and private equity. It usually targets businesses that already have solid revenue and want to expand further without the extreme risk profile of an early-stage startup. Growth capital deals often come with less dilution than a typical VC round because the business is already de-risked by real performance.
Revenue-Based Financing
Instead of giving up equity, you repay investors as a percentage of your monthly revenue until a set amount is paid back. This works well for businesses with consistent recurring income, like SaaS companies, since repayment naturally adjusts to how the business performs.
Grants and Government Programs
Some grants are real free money with no repayment, but many so-called “grant” offers online are actually loan programs in disguise. Always check whether repayment is required before treating any offer as a grant.
Venture Debt
A loan designed specifically for funded startups, usually taken alongside equity funding. Debt financing has actually grown in importance recently, since more founders are trying to extend their runway without further diluting ownership.
How to Pick the Right Option for Your Business
There’s no universal “best” choice. Here’s a simple way to think about it:
- If you want to keep full ownership and can grow slowly, bootstrap or use a bank loan.
- If your revenue is recurring and predictable, revenue-based financing avoids dilution while matching repayment to your cash flow.
- If you need a large amount of capital fast and are comfortable giving up equity, venture capital or growth equity makes sense.
- If you qualify for one, non-dilutive grants are the cheapest capital you’ll ever get — just verify the terms first.
A good rule: match the funding type to what the money is actually for. Short-term working capital needs don’t need equity funding. Long-term expansion into new markets often does.
Mistakes That Cost Founders Money and Control
Raising too early. Investors want proof, not promises. Applying for growth capital before you have real revenue numbers usually leads to rejection or bad terms.
Ignoring dilution math. Giving up 20% equity sounds fine until you do it three funding rounds in a row and realize you now own a minority of your own company.
Not reading the fine print. Some “growth funding” offers online are marketing terms for high-interest loans. Always confirm repayment terms, interest rates, and whether personal guarantees are required.
Applying without financial documents ready. Lenders and investors move on quickly if you can’t produce clean financial statements, cash flow projections, or a clear use-of-funds plan.
Treating funding as a one-time event. Most growing businesses use a mix of funding types over several years, not one big round that solves everything.
Steps to Prepare Before You Apply
- Get your financial statements in order — at least 12 to 24 months of clean records.
- Know exactly how much you need and what it will be spent on.
- Check your eligibility for grants or government-backed programs first, since these are the cheapest capital.
- Compare at least two or three funding types before committing to one.
- Talk to a financial advisor or accountant before signing any funding agreement, especially one involving equity.
Frequently Asked Questions
Is growth funding the same as a startup loan?
No. Startup loans usually help launch a new idea. Growth funding supports a business that already has customers and revenue, and wants to expand further.
Do I need to give up equity to get growth funding?
Not always. Bank loans, revenue-based financing, and some grants let you raise capital without giving up ownership. Equity funding is only one path among several.
How much growth capital can a business typically raise?
It varies widely by industry and revenue size, but growth capital deals often range from a few hundred thousand dollars to tens of millions, depending on the business’s size and proof of traction.
Are online “growth funding” programs safe?
Some are legitimate, but not all. Always verify whether an offer is a grant, a loan, or an investment before applying, and check for a real, named organization behind it.
What do investors look for before offering growth funding?
Steady revenue, strong customer retention, healthy profit margins, and a clear, realistic plan for how the funds will be used.
Final Thoughts
Growth funding isn’t about finding the biggest check available — it’s about finding the right fit for where your business actually is. A business with steady recurring revenue rarely needs the same funding path as one chasing rapid, high-risk expansion. Take time to understand your numbers, compare your real options, and read every term before you sign. That’s what actually protects your business in the long run, not the size of the funding round.
Explore More:
